

FASB ASU 2023-09: Preparing for New Income Tax Disclosure Requirements
The Bottom Line
The Financial Accounting Standards Board (FASB) issued ASU 2023-09, Improvements to Income Tax Disclosures, to provide greater transparency into companies’ income tax expense and income taxes paid.
This ASU significantly expands what companies must disclose about their effective tax rate and the cash income taxes they pay. It is now effective for both public business entities (fiscal years beginning after December 15, 2024) and all other entities (fiscal years beginning after December 15, 2025). Implementation may require additional data collection, analysis, documentation, and updates to existing reporting processes. This alert highlights the changes and steps you can take to prepare.
These changes affect financial statement disclosures; they do not change how income tax expense is measured.
Private and other non-public entities are not required to produce the numeric tabular rate reconciliation, but they must still qualitatively describe the categories and jurisdictions driving a significant difference between the statutory and effective rate — and they face the same income-taxes-paid disaggregation requirement as public companies.
Who Is Affected, and When
| Entity Type | Effective For | Numeric Rate Reconciliation? |
| Public business entities | Annual periods beginning after 12/15/2024 (CY2025) | Required — tabular, $ and % |
| All other entities (private, not-for-profit, etc.) | Annual periods beginning after 12/15/2025 (CY2026) | Not required — qualitative disclosure only |
These requirements apply to entities subject to ASC 740. Applicability to pass-through and tax-exempt entities depends on whether they have income taxes within the scope of ASC 740.
Early adoption is permitted. The amendments are applied prospectively, though retrospective application is permitted.
Why This Is More Than a Disclosure Update
The new rules don’t change how tax expense is measured — they change how much detail must sit behind the numbers you already report. In practice, that means:
- Jurisdiction-by-jurisdiction tracking of cash taxes paid, which many provision processes and general ledgers are not currently structured to isolate cleanly.
- For public business entities, mapping effective tax rate reconciling items into the ASU’s eight prescribed categories, as applicable, and providing additional detail by nature and/or jurisdiction when required under the applicable 5% disclosure thresholds.
- Evaluating the applicable 5% disclosure thresholds each year and documenting the judgment behind what is, and isn’t, broken out.
- Building (and maintaining) a repeatable process and supporting workpapers auditors will expect to see, not just a one-time schedule.
Early preparation can make the disclosure process smoother. Gathering the necessary information and coordinating with your GRF engagement team and tax preparer before year-end can help minimize last-minute requests and keep financial reporting on track.
Questions?
We’re happy to walk through how ASU 2023-09 applies to your specific facts and to scope the transition work together. Please reach out to your engagement team to schedule a readiness discussion.
This alert is provided for general informational purposes only and does not constitute accounting, tax, or legal advice. Please consult your engagement team regarding how these requirements apply to your specific circumstances.



Join us online!
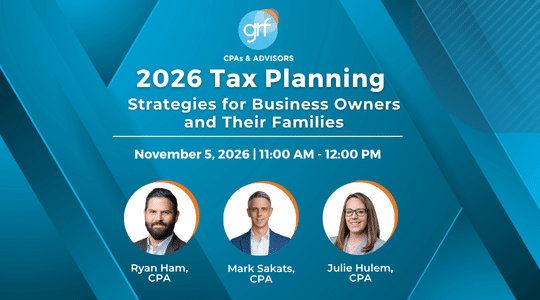
Our annual Tax Planning Webinar is November 5th, where our team will walk through comprehensive year-end strategy for pass-through business owners and their personal returns.